
Most sellers let Amazon charge advertising to their account balance every $500 and never think about it again.
That default is costing you two things at once: the free credit you would get by paying later, and the cashback you would get by paying with a card.
This is a one-time project. A week or two of admin, and it earns quietly in the background forever after.
Prefer to watch? One hundred and forty-five seconds on raising your billing increment, switching ad spend to a credit card, and sizing the cashback against your net margin.
The two levers
1. Raise the billing threshold. Amazon bills advertising in increments — $500 by default, and it will raise that to $5,000 or $10,000 on request. Fewer, larger charges means each one lands later.
2. Pay by credit card instead of account balance. That adds your card's own statement period on top.
Stacked, the two put roughly 60 days between spending on ads and paying for them — free credit, from money you were spending anyway.
Why the threshold matters more than it looks
At a $500 increment and $30,000 a month of ad spend, you are charged sixty times a month — effectively paying same-day.
At a $10,000 increment, three charges a month. The average dollar of ad spend now sits unpaid for days rather than minutes, and that difference is working capital.
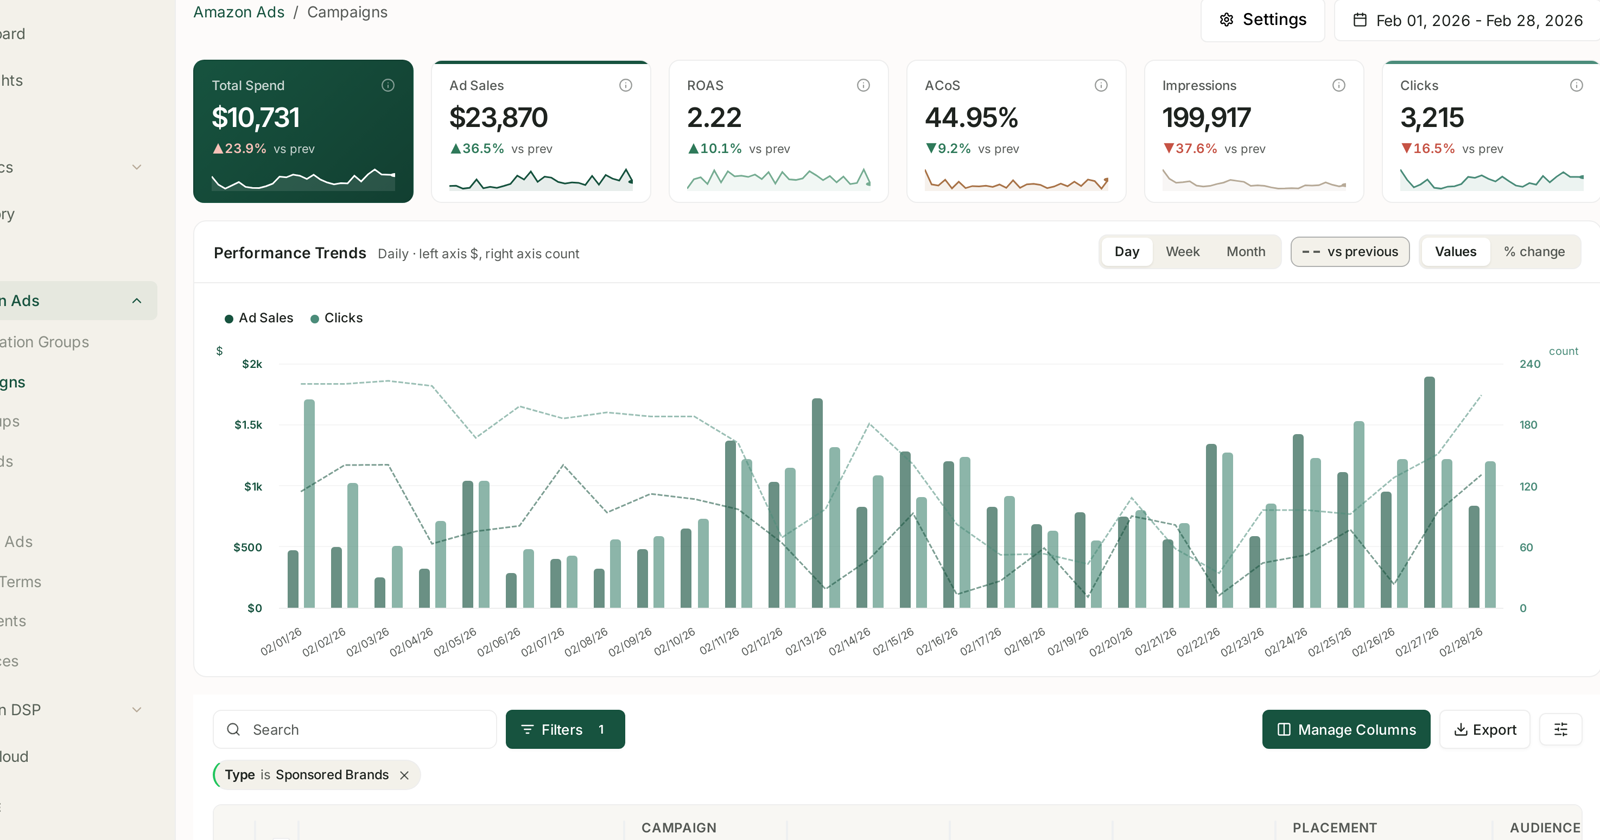
Check your actual monthly spend first, because it decides which increment is realistic to ask for.
How to request the increase
- Go to the advertising campaign manager.
- Open the help icon and choose Support Center.
- Pick Billing and Payments, then Contact us.
- Choose Payments and Invoicing → Payment frequency and credit ladder.
- Start a live chat and make the request directly.
A message that works:
"Please adjust my payment ladder to $10,000. My credit card is [last four], limit [amount]. My Ads ID is [entity ID]."
Your Ads ID is in the console URL — the value after entityId=.
Your card limit must exceed the increment you are asking for. Requesting a $10,000 ladder on a $5,000 limit gets declined on the spot.
And expect a ladder, not a leap. Amazon raises these gradually. If you are refused for low spend or a non-US account, keep spending consistently and ask again in a month or two.
Paying by card
Change the payment method in the campaign manager from account balance to a card.
Then work out what the cashback is actually worth, because at real ad spend it is not a rounding error:
| Monthly ad spend | Cashback rate | Extra profit per year |
|---|---|---|
| $10,000 | 2% | $2,400 |
| $30,000 | 2% | $7,200 |
| $30,000 | 3% | $10,800 |
And read that against your margin. At a 10% net margin, $10,000 of cashback is worth the same as $100,000 of additional sales — about $8,000 a month more revenue you did not have to sell.
That comparison is why this is worth a fortnight of admin. Very little else in the business produces that much profit for that little work.
Choosing the card
Compare candidates on the same six questions, so the answers line up:
What is the spending limit, monthly and annually?
What cashback rate, and in what form — cash, statement credit, or points?
Can you add more cards if you outgrow the limit, and how many?
Can it be linked to an online business account, or only a traditional bank?
What are the foreign-currency fees, if you pay suppliers in other currencies?
What is the statement and due-date cycle — this is the part that determines your actual float.
Then negotiate. Tell the provider you have compared others and had better terms on a specific dimension, and ask them to match. Card terms are more negotiable than most sellers assume.
Plan the limit before you need it
Calculate how much ad spend the card can absorb at your current rate, and at the rate you expect during Q4.
A card that hits its limit mid-month stops the whole arrangement — Amazon fails the charge, and you are back to account balance at the worst possible moment.
So work out when you will need a second card, and apply before peak season, not during it.
The wider version of the same idea
Cashback on ads is one of four places money leaks on its way through the business:
Cashback on card spend — covered above.
Receiving payouts from Amazon — aim for zero fees.
Paying suppliers, freight and team — keep transfer fees minimal.
Currency conversion — can be as low as around 0.15%, and is frequently many times that by default.
Audit all four, then fix the worst one. If only cashback is weak, a card solves it. If several are weak, the account you bank through is the problem.
Common mistakes
Leaving the $500 default in place, which is the whole cost of this article.
Asking for a threshold above your card limit, and getting an automatic no.
Treating a refusal as final rather than as a ladder you climb with consistent spend.
Choosing a card on headline rate alone, ignoring the limit and the statement cycle.
Letting the card hit its limit in Q4, exactly when ad spend peaks.
Fixing the cashback and ignoring the conversion rate, which on an importing business is often the larger leak.
Related
- Better Payment Terms From Suppliers and Freight — the larger free credit line.
- Where Your Margin Actually Goes — the rest of the cost stack.
- Campaigns: Budgets, Placement and Audience Adjustments — where the spend numbers come from.